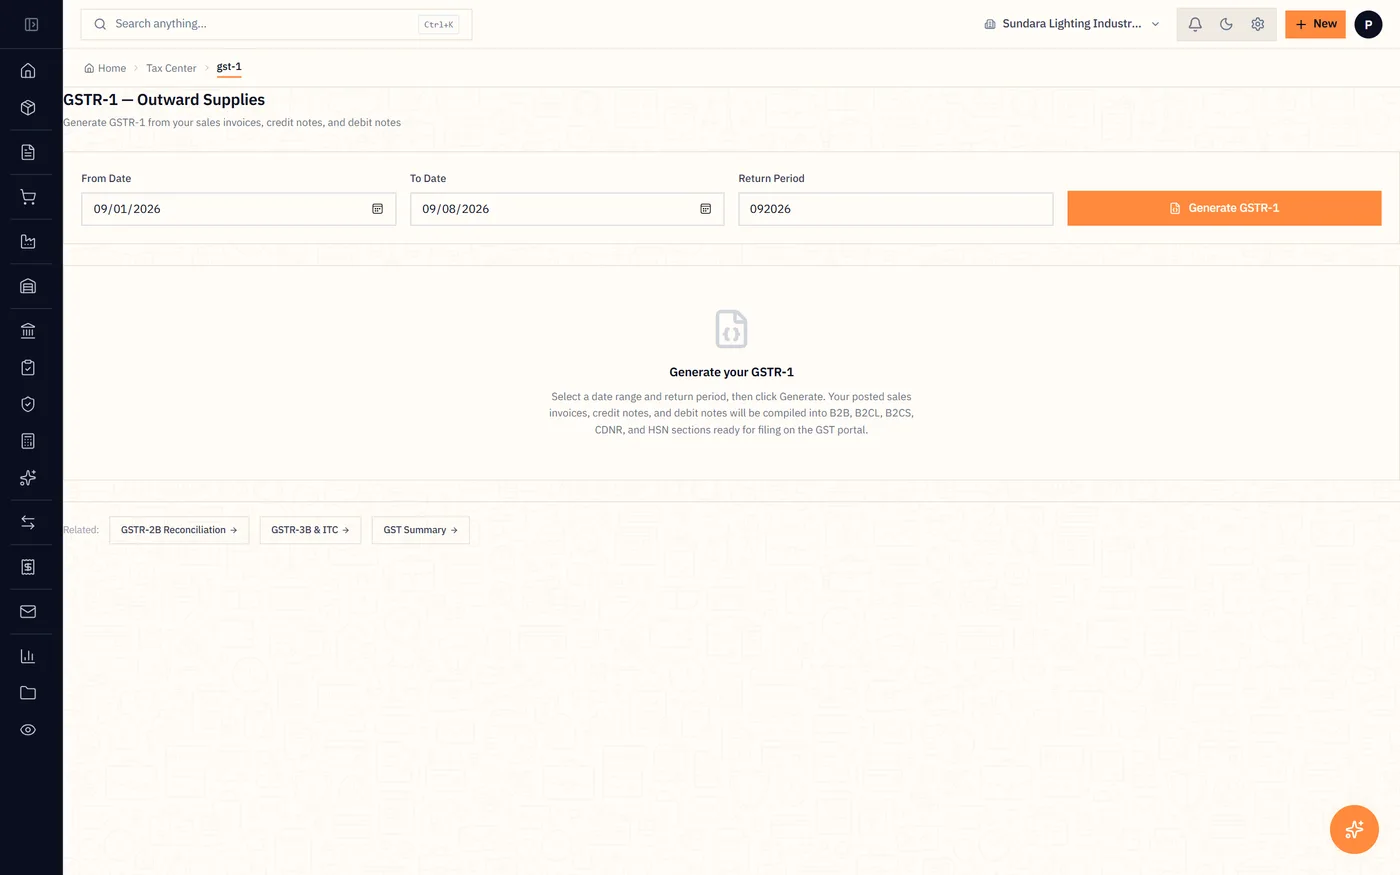
GSTR-1 prepared from posted vouchers — filed figures trace to the ledger.
GST · Returns
GSTR-1 is assembled from your vouchers, not rebuilt from memory on the 18th. Tax was split when the invoice was raised; the return simply reports it.
GSTR-1 prepared from posted vouchers — filed figures trace to the ledger.
Invoice by invoice from the vouchers, B2B and B2C split as the law requires.
Counterparty GSTIN, place of supply and HSN checked while there is time to fix.
Output tax meets permitted credit; the cash figure falls out of the two.
Quarterly filers push invoices monthly so customers are not left waiting for credit.
The annual reconciliation, from the same ledgers as everything else.
Last quarter's correction stays visible this quarter.
The return is assembled from what you recorded. Filing stays a deliberate act.
| GSTR-1 | GSTR-2B | GSTR-3B | Annual | |
|---|---|---|---|---|
| What It Does | Declares Outward By The 11th Invoice Level | Verdict On Credit Static From The 14th Supplier Filed | Pays The Difference By The 20th Summary Level | 9C Reconciliation Annual Books Vs Returns |
| From Autobooks | Prepared From Vouchers | Matched To Purchase Register | Output Meets Permitted ITC | Same Ledgers, Whole Year |
CGST and SGST intra-state, IGST inter-state — never both, never mixed. Computed server-side by the same engine that posts the voucher, so nobody reconstructs a place of supply from memory in the last week.
Prepared here, filed by you — we never hold your portal credentials.
Thirty minutes on your own data, nothing installed.